On This Page
The difference between compound interest vs. simple interest comes down to how interest is calculated over time and how much growth or cost results from that calculation. Both are ways of measuring interest on money, but they behave very differently depending on whether interest is earned only on the original amount or also on accumulated interest.
Understanding compound interest vs. simple interest is important because it affects everything from savings growth to borrowing costs. The structure of the interest calculation can significantly change how money grows or how much a loan ultimately costs over time.
What Simple Interest Means
Simple interest is the more straightforward of the two. It is calculated only on the original amount of money, also known as the principal. This means the interest amount does not change based on previously earned interest.
Instead, it stays consistent over time as long as the principal and interest rate remain the same. Because of this, simple interest tends to be easier to calculate and more predictable. Simple interest is often used in certain types of short-term loans or financial arrangements where the structure is designed to remain stable over time.
What Compound Interest Means
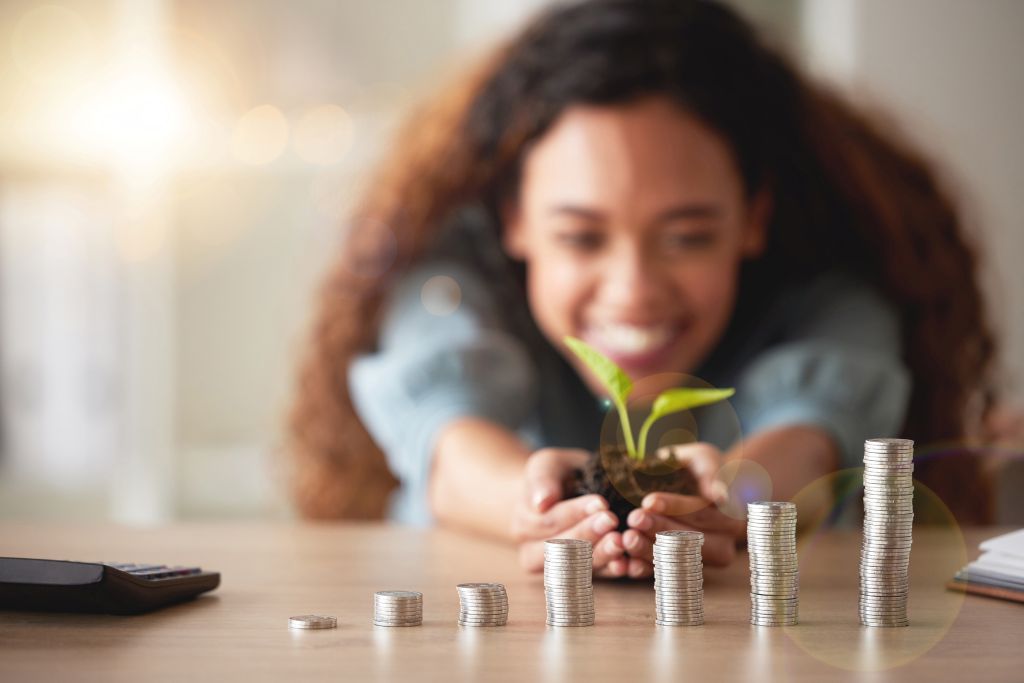
Compound interest, on the other hand, works by calculating interest not only on the original principal but also on any interest that has already been added. This creates a snowball effect over time.
As interest accumulates, it becomes part of the balance that earns additional interest in future periods. The longer money remains in a compound interest structure, the more pronounced this effect becomes.
Compound interest is commonly associated with savings accounts, investment growth, and long-term financial planning because of its ability to increase balances over time when conditions remain consistent.
Key Difference in How They Grow
The main distinction between compound interest and simple interest is how growth is calculated over time. Simple interest grows in a linear way because it is always based on the original amount.
Compound interest grows in a more dynamic way because each new period builds on the previous total. This means that as time passes, the difference between the two can become more noticeable, especially over longer periods.
Time plays a major role here. The longer the duration, the more compound interest tends to separate itself from simple interest in terms of total growth or cost.
How Interest Applies in Borrowing and Saving
Both methods are used in different financial contexts. Simple interest is often seen in certain lending arrangements where repayment amounts are predictable and do not change based on accumulated interest.
Compound interest, on the other hand, is more commonly used in savings and investment-related accounts. In those cases, the goal is often to allow balances to grow over time as interest continues to build on itself.
This difference in application is important because it affects whether interest works in favor of the account holder or increases the total cost of borrowing.
A Simple Comparison Over Time
The difference between compound interest and simple interest becomes clearer when looking at how each behaves over multiple time periods. With simple interest, the growth remains steady because it is always based on the original amount. With compound interest, growth accelerates as each period adds new interest to the balance.
Over time, this can create a larger gap between the two methods even if they start with the same principal and rate.
Why Compound Interest is Often Emphasized
A major reason compound interest vs. simple interest is frequently discussed in personal finance is that compound interest plays a central role in long-term financial growth. Even small differences in how interest is calculated can lead to meaningful differences over time.
This is especially relevant in long-term savings or planning scenarios, where time allows compounding to have a greater impact. Because of this, understanding how compounding works helps explain why long-term financial strategies often focus on consistency and duration.
Real-World Financial Context
In everyday financial life, compound interest vs. simple interest shows up in different ways depending on the product or agreement. Some lending structures use simple interest for clarity and predictability, while many savings and growth-oriented accounts rely on compounding mechanisms.
In structured financial arrangements, understanding how interest is applied can also help clarify how values are calculated over time. Even when payments are fixed or scheduled, the underlying financial structure may still be influenced by interest calculations in the background.
The Broader Takeaway of Compound Interest vs. Simple Interest
Overall, these different types of interest explain how money grows or accumulates based on the method used to calculate interest. Simple interest provides steady and predictable growth based only on the original amount, while compound interest builds over time by adding interest on top of previously earned interest.
Both methods have their place depending on the financial situation, but the way they behave over time can lead to very different outcomes. Understanding this difference helps provide a clearer picture of how money changes over time in both saving and borrowing contexts.